
Library | ESG issues
Reporting & Disclosures
Reporting and disclosures provide transparency on a company’s financial performance, strategy, and sustainability practices. Clear, reliable disclosures improve stakeholder trust, inform investment decisions, and drive corporate accountability.
Team Altiorem recommends


Refine
708 results
REFINE
SHOW: 16


Natura Future P&L Tool
The Natura Future P&L Tool is a free digital platform that enables businesses to measure and monetise their environmental, social, and human impacts. It helps finance professionals integrate ESG externalities into traditional financial analysis to assess a company’s total value creation.
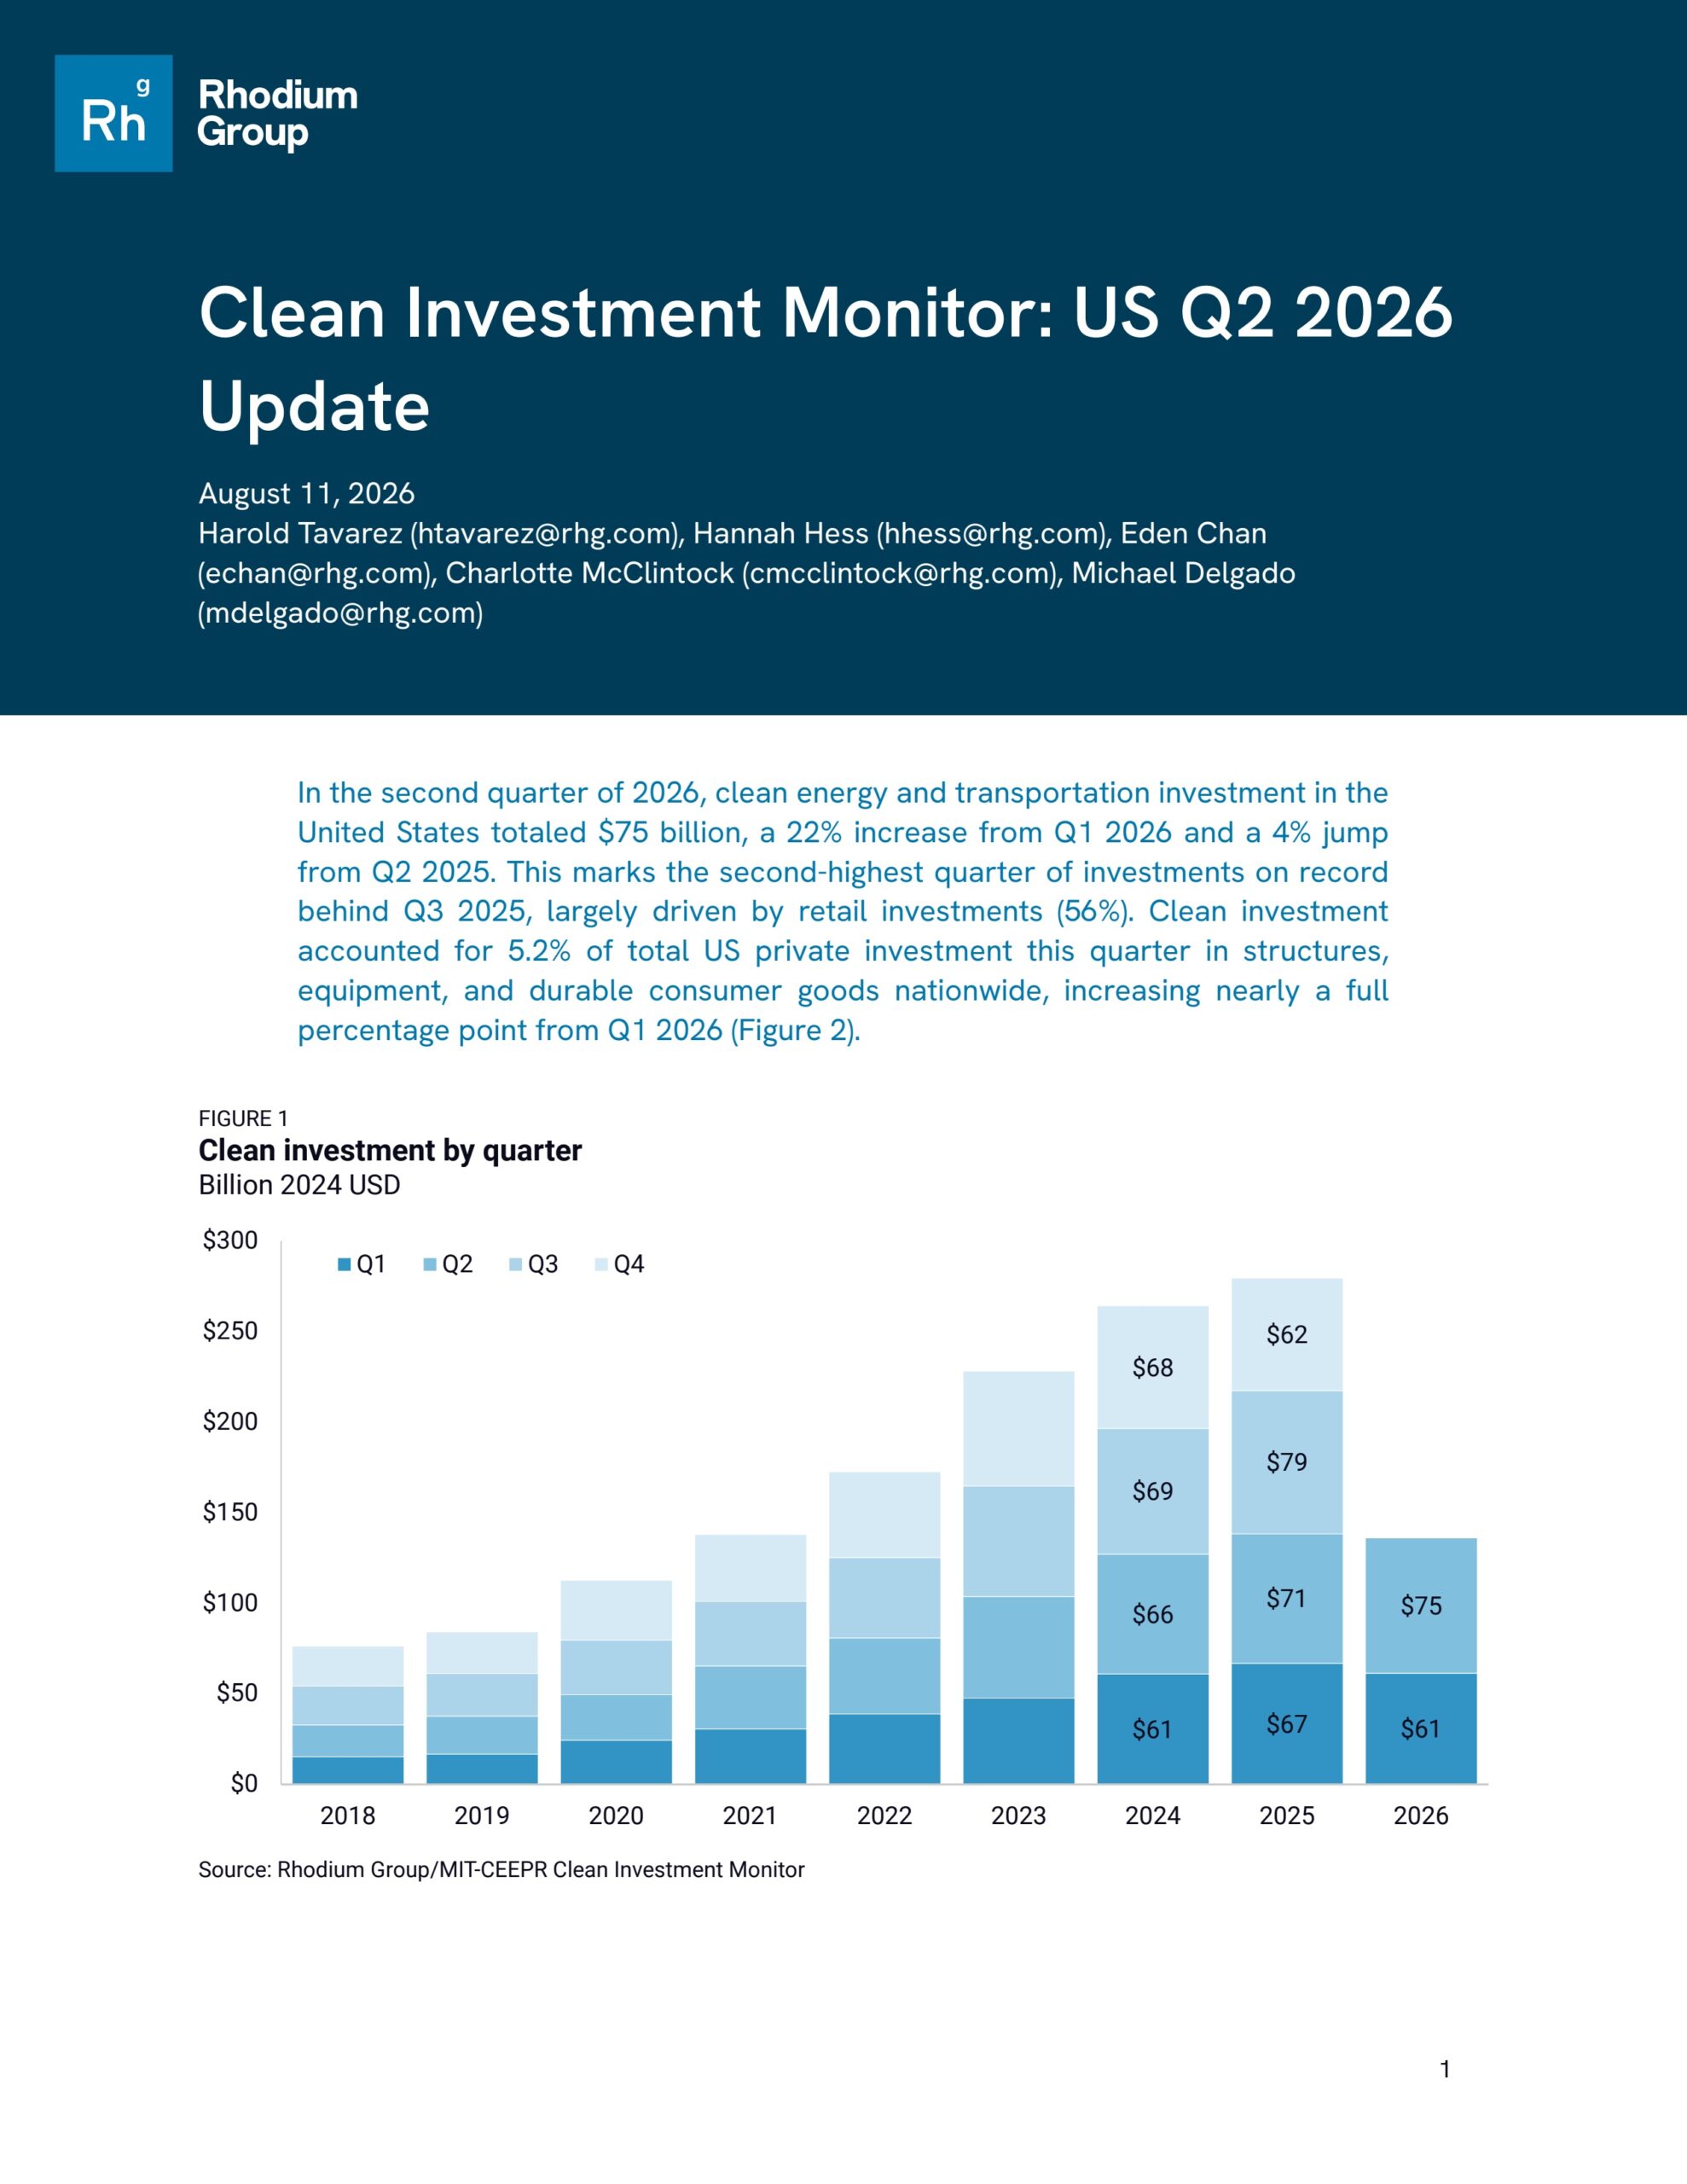
Clean investment monitor: US update series
The Clean Investment Monitor: US Update is a benchmark series providing a comprehensive database of clean energy and transportation investment across the United States. Produced by Rhodium Group and MIT-CEEPR, it tracks the manufacture and deployment of greenhouse gas emission-reducing technologies across manufacturing, energy and industry, and retail segments.
Greenwashing as aspirational signaling: From burden to benefit?
This research analyses the transition of sustainability disclosures from voluntary practices to mandatory legal frameworks in the US and EU. It examines the 'greenwashing enforcement gap' and argues that aspirational signalling, despite inaccuracies, can drive institutional change and attract a prosocial workforce to improve corporate conduct.
Connecting nature, climate, and capital: From data to decisions: Natural capital accounting in practice
This research explores Natural Capital Accounting in New Zealand, focusing on the SEEA EA framework. It provides practical steps for businesses to quantify nature-related risks and dependencies. Through case studies, it demonstrates how environmental data informs investment, lending, and strategic management to enhance organisational resilience and long-term value.
Asking better questions on nature: For chief financial officers
This guide helps Chief Financial Officers integrate nature-related issues into financial decision-making. It outlines how to identify dependencies, assess risks and opportunities, and respond to evolving disclosure expectations. The report emphasises nature as a core driver of performance, resilience and long-term value creation within the TNFD framework.
International Ethics Standards for Sustainability Assurance (including International Independence Standards) and other revisions to the Code relating to sustainability assurance and reporting
IESBA’s final pronouncement establishes ethics and independence standards for sustainability assurance by introducing Part 5 to the Code. It outlines five fundamental principles and a conceptual framework to address threats, alongside requirements for tax planning, responding to non-compliance, and leader rotation for public interest entities.
GRESB Guides
GRESB Guides is a comprehensive documentation hub providing methodology, reference manuals, and scoring documents for GRESB’s global ESG benchmarks in real estate and infrastructure. It helps finance professionals navigate reporting requirements and interpret sustainability performance data.
Science Based Targets Network Target Tracker
The SBTN Target Tracker is a public database that monitors companies setting science-based targets for nature. It provides finance professionals with verified data to assess corporate progress on land, water, and biodiversity goals.
Climate Data Store (CDS)
The Climate Data Store (CDS) is an open-access platform providing authoritative climate datasets, including historical reanalysis and future projections. It enables finance professionals to assess physical climate risks, track greenhouse gas emissions, and integrate evidence-based environmental data into ESG reporting and investment analysis.
European state of the climate report series
The European State of the Climate is an annual flagship report series providing structured descriptions and analyses of climate conditions in Europe. Published by the Copernicus Climate Change Service and the World Meteorological Organization, it evaluates Earth system variables and key climate events alongside policy actions for biodiversity.
SBTi Corporate Net-Zero Standard version 2.0
The SBTi Corporate Net-Zero Standard Version 2.0 provides a framework for science-based target setting and implementation. It introduces an implementation hierarchy, transition planning requirements, and a voluntary Ongoing Emissions Responsibility programme. The standard focuses on context-specific targets and best-efforts delivery to reach net-zero by 2050.
Global MDB Investments in Petrochemicals Tracker
An interactive database and map developed by IEEFA and IAP that tracks over USD 10 billion in petrochemical investments from 16 multilateral development banks, highlighting institutional exposure to fossil-fuel-intensive projects.
Transition Plan Taskforce Resources
A suite of guidance materials, including the TPT Disclosure Framework and sector-specific guides, designed to help organisations create and disclose robust climate transition plans in alignment with IFRS S2.
Climate-related transition planning: Voluntary guidance
This voluntary guidance from the Australian Treasury helps organisations develop climate-related transition plans. It details a four-stage process—assessing position, setting ambitions, planning actions, and implementation—to manage risks and align with Australia’s net zero targets, building on international standards and domestic policy to enhance business resilience.
BSI Net Zero Barometer Report Series
This benchmark series examines the UK business landscape's transition to net zero. It tracks commitment levels, drivers, and barriers among senior decision-makers. The research explores how organisations are reframing sustainability as a commercial necessity and highlights the demand for government support, financial incentives, and standardised guidance to achieve 2050 targets.
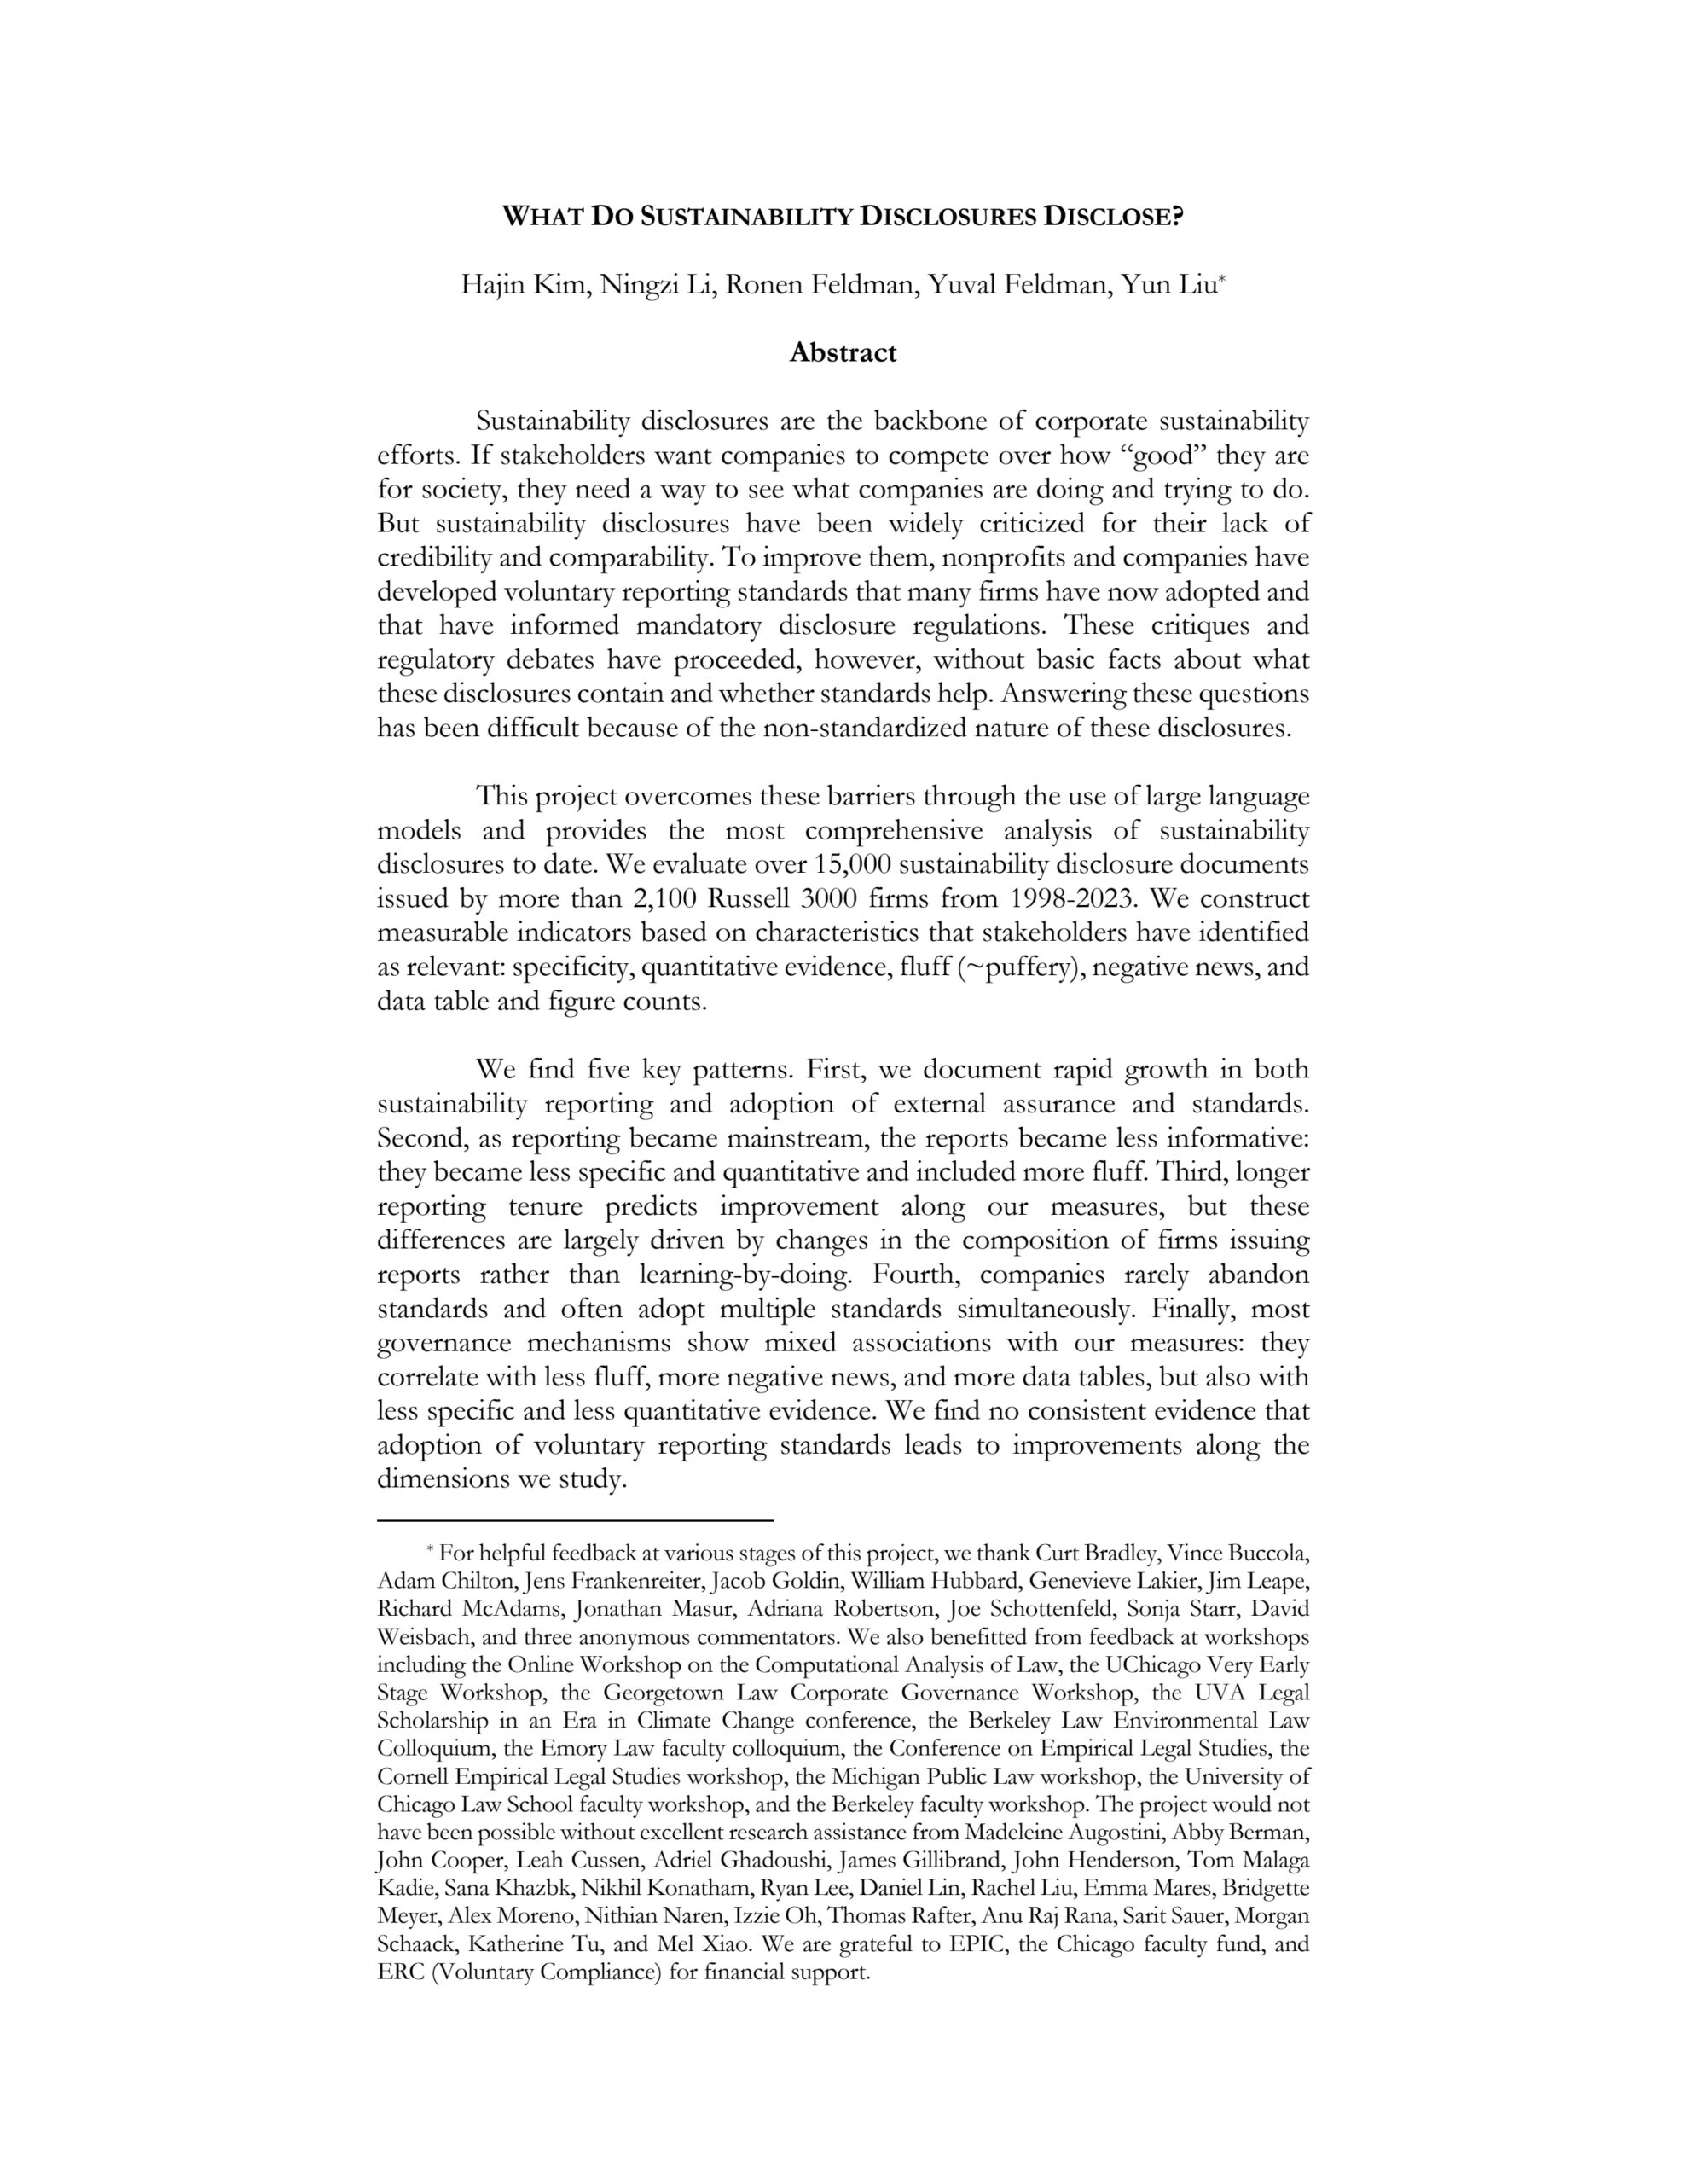
What do sustainability disclosures disclose?
This research analyses over 15,000 sustainability disclosures from Russell 3000 firms. It finds that while reporting has surged since 2015, informative quality has declined. Adoption of voluntary standards yields mixed results, correlating with reduced 'fluff' but lower narrative specificity. Improvements primarily reflect selection effects rather than organisational learning.


