
Library | ESG issues
Oversight, Assurance & Audit
Effective oversight, assurance, and audit are essential for organisations to manage risks and ensure the integrity of both financial and sustainability reporting. Boards and senior executives are responsible for overseeing risk management processes, obtaining assurance that principal risks are identified, managed, and monitored, and ensuring the effectiveness of internal controls. Audits, whether financial or sustainability-focused, involve independent evaluations of an organisation’s reports and controls to provide stakeholders with confidence in the accuracy and reliability of disclosed information.
Team Altiorem recommends

Refine
226 results
REFINE
SHOW: 16


Taskforce on official standards and the Green Bond Principles. Phase 1: Comparison of the Green Bond Principles and the European Green Bond Standard
This report compares the voluntary Green Bond Principles with the regulatory European Green Bond Standard. It identifies high proximity and synergy between the frameworks, providing guidance on how issuers can navigate both sets of requirements to enhance transparency and facilitate global investor recognition in the sustainable finance market.
Governing climate credibility: Reviewing the governance of climate and sustainability standards
An independent review of governance across five leading climate standard-setters: GHGP, GRI, ISO, ISSB, and SBTi. The report evaluates structures, finance, and independence, identifying strengths and transparency gaps. It offers recommendations to enhance accountability, resource governance effectively, and ensure long-term credibility for net zero objectives.
Public finance in the digital era: Emerging themes 2026
This report explores emerging themes in digital-era public financial management (PFM) for 2026. It examines the integration of artificial intelligence, digital public infrastructure, and earth observation to improve fiscal oversight, tax administration, and public welfare, while highlighting risks from declining international aid and proprietary software lock-in.
International Ethics Standards for Sustainability Assurance (including International Independence Standards) and other revisions to the Code relating to sustainability assurance and reporting
IESBA’s final pronouncement establishes ethics and independence standards for sustainability assurance by introducing Part 5 to the Code. It outlines five fundamental principles and a conceptual framework to address threats, alongside requirements for tax planning, responding to non-compliance, and leader rotation for public interest entities.
Who funds and who pays: The funding of solar geoengineering, 2020–2025
This report examines the dramatic tenfold increase in solar geoengineering funding between 2020 and 2025. It highlights the dominance of US and UK tech billionaires and government agencies in financing research, raising concerns about transparency, democratic oversight, and the marginalisation of Global South interests in climate policy.
Seeing the goal, missing the truth: Human accountability for AI bias
Research demonstrates that Large Language Models exhibit purpose-conditioned bias when informed of downstream tasks. Goal-aware prompting leads to in-sample overfitting and inflated performance before knowledge cutoffs. Results indicate that disclosing objectives compromises neutrality, necessitating the separation of measurement and evaluation in AI-assisted workflows to ensure statistical validity.
CPA-Zicklin Index of Corporate Political Disclosure and Accountability
This benchmark series evaluates corporate political disclosure and accountability practices among major US companies. It provides a structured analysis of transparency, board oversight, and spending policies for the S&P 500 and Russell 1000, enabling stakeholders to assess political risk and governance standards across different industries.
Climate-related disclosures: Insights from our reviews 2026
This Financial Markets Authority report reviews 62 climate statements from the second reporting period in Aotearoa New Zealand. It identifies improvements in reporting structures but highlights gaps in physical risk analysis and assurance compliance. Future monitoring will focus on education to improve data substantiation and risk disclosure quality.
Fragmentation of shareholder power
This research examines how fund proliferation and stewardship decentralisation affect corporate governance. It finds that supply-driven growth weakens oversight, while demand-driven expansion by incumbents can strengthen it. Competitive adoption of pass-through voting improves investor preference alignment but often reduces monitoring incentives and firm value.
The current state of BRSR in corporate India 2.0
This report analyses Business Responsibility and Sustainability Reporting (BRSR) data from 300 Indian companies over three years. It identifies progress in disclosure quality, energy intensity trends, and assurance practices. Recommendations focus on standardisation and sector-specific guidance to enhance the decision usefulness of sustainability data for investors and regulators.
Assessing the quality of adaptation finance tool
A CPI decision-support tool for public finance providers to assess adaptation finance quality across project, market, and system levels.
Rate the raters series
Rate the Raters is a benchmark series by the ERM Sustainability Institute tracking corporate perceptions of ESG rating agencies. It examines quality, usefulness, trust, and engagement with ESG raters across regions and industries, offering a longitudinal view of the evolving ESG ratings landscape for companies and investors.
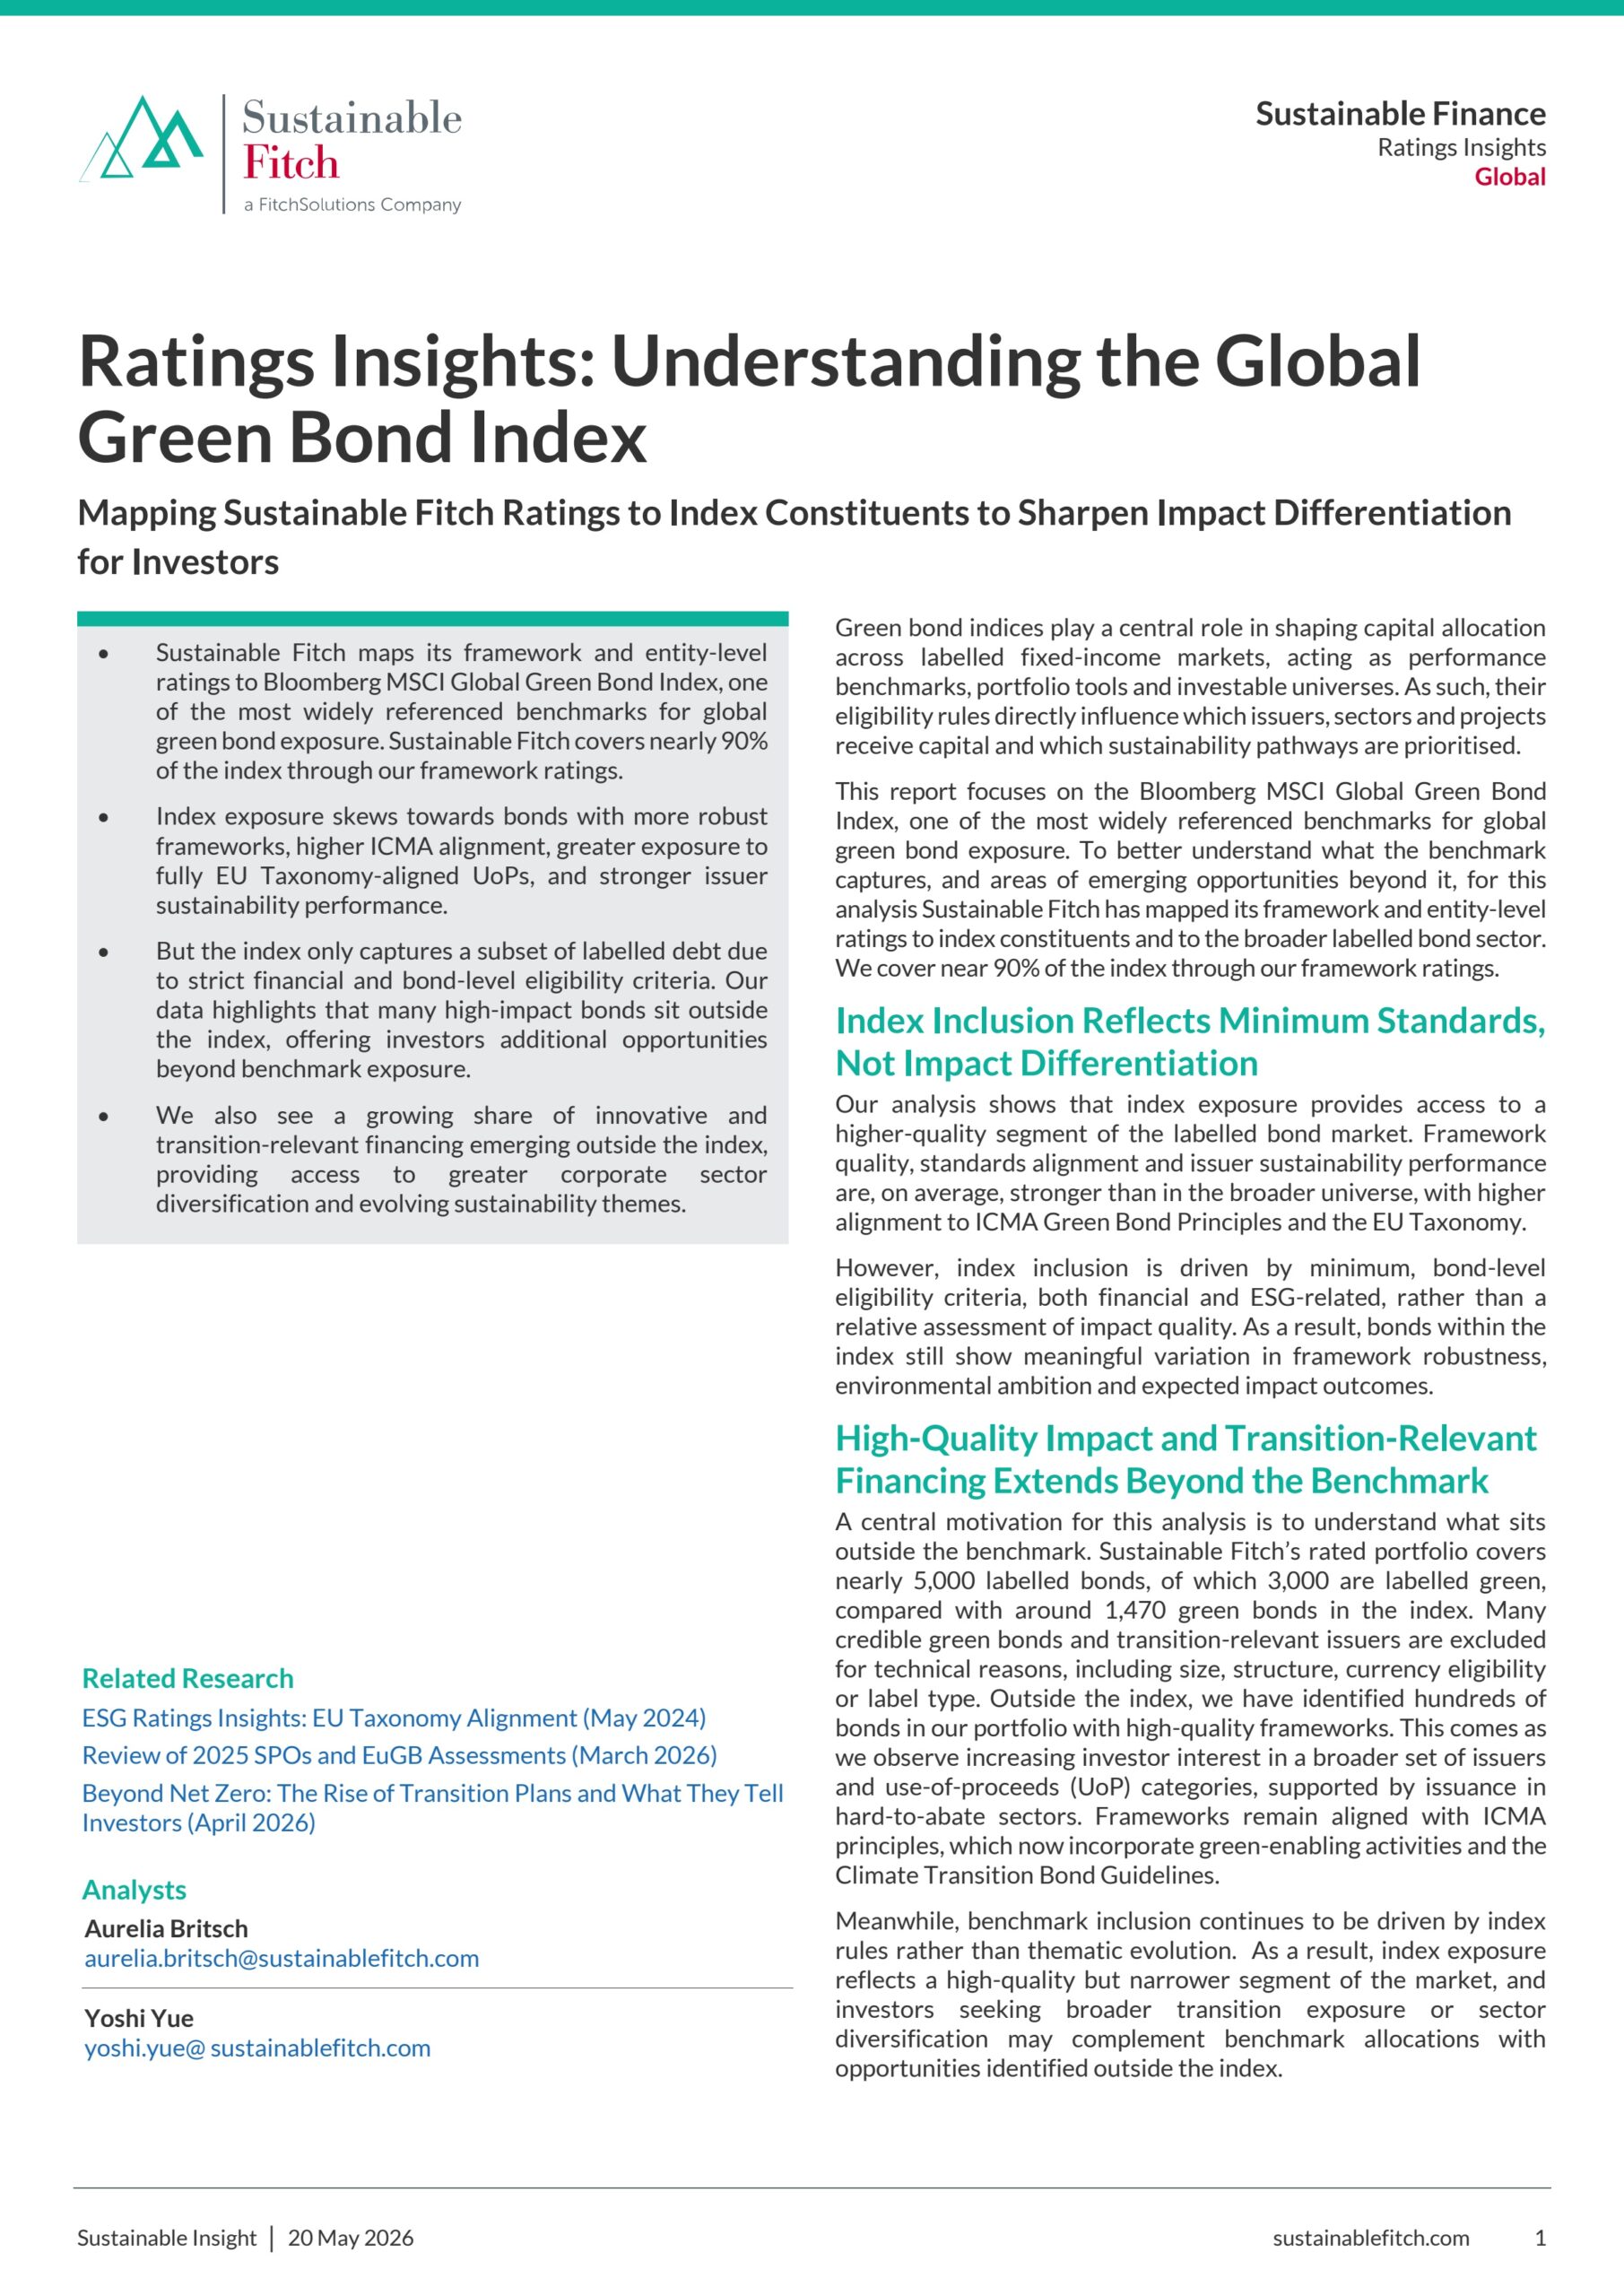
Ratings insights: Understanding the global green bond index
Sustainable Fitch maps its framework and entity-level ratings to the Bloomberg MSCI Global Green Bond Index, covering 88% of index bonds. While index constituents show stronger framework quality and ICMA alignment than the broader market, many high-quality and transition-relevant bonds sit outside the benchmark due to financial eligibility constraints.
Ethical & impactful usage of AI
This report by Do Harvey outlines an ethical framework for AI usage, highlighting environmental impacts, security risks, and bias concerns. It advocates for transparent, client-opt-in adoption underpinned by human oversight, and summarises five modes of AI use to guide teams in making values-aligned, informed decisions.
Responsible AI in practice: 2025 global insights from the AI Company Data initiative
This report analyses publicly disclosed data from 2,972 companies across 11 sectors, revealing a significant gap between AI adoption and governance maturity. Only 13 per cent align their strategy with a formal framework, and few demonstrate adequate worker protections, ethical impact assessments, or training data oversight.
Optional shareholder voting
This paper examines optional shareholder voting by institutional managers (IMs) using newly available SEC data on say-on-pay votes. Only 44% of IMs vote, yet their aggregate voting footprint is twice that of mutual funds. IMs use voting as a monitoring tool, with larger positions associated with greater opposition to management.


