
Library | Sustainable Finance Practices
Industry standards and guidance
Voluntary standards, non-legislative frameworks, methodologies, and best-practice guidance that support financial institutions in achieving sustainability objectives.
Refine
389 results
REFINE
SHOW: 16


Unlocking finance for nature-based solutions (NbS) in Indian cities: Learnings and insights from case studies
This report examines nine Indian nature-based solutions (NbS) case studies to evaluate financing mechanisms and institutional frameworks. It highlights the importance of reducing technical risk through feasibility studies, aligning with national policies, and sequencing capital to support project scalability and long-term sustainability in urban environments.
Peer groups matter: Comparative industry effects in ESG rating disagreement
This research identifies the 'comparative industry effect'—differences in industry classification and peer group construction—as a major driver of ESG rating divergence. It explains 30% of industry-level score differences, particularly affecting environmental ratings and firms with limited public disclosure or complex ownership structures.
Investing in water-related and dependent infrastructure: Risks, considerations, and opportunities
This report examines water risks as systemic financial threats to infrastructure. It proposes a seven-step decision framework to integrate ecosystem services into project appraisal and financing. Through case studies in Africa and Asia, it advocates for hybrid green-grey solutions and innovative financial mechanisms to address the global water infrastructure gap.
IPSASB SRS 1, Climate-related disclosures
This IPSASB standard establishes principles for public sector entities to disclose climate-related risks and opportunities. Aligned with IFRS S2, it mandates disclosures regarding governance, strategy, risk management, and performance metrics. The standard prioritises accountability for long-term fiscal sustainability and service delivery, with an effective date of 1 January 2028.
Unlocking textile circularity in the EU: From challenges to opportunities
This report examines barriers and enablers for scaling up textile recycling in the EU. Combining literature reviews with 20 stakeholder interviews, it identifies technological, financial, and regulatory constraints. Recommendations include supporting demand-side measures, funding sorting technology research, and strengthening value chain collaboration to achieve circularity targets.
Public procurement and AI governance: Developing a strategic framework for middle powers
This report evaluates how 'AI middle powers' can use public procurement as a strategic governance tool to mitigate risks from foreign-led frontier AI. It proposes a framework of contractual guarantees and recommends international coordination to increase bargaining leverage, enhance visibility, and secure data sovereignty against technological dependencies.
Measuring what matters: A practical framework to integrate health into urban climate action
This report introduces a practical framework for integrating health co-benefits into urban climate monitoring. It details a five-step process for selecting robust indicators across air pollution, active travel, and sustainable diets. The framework helps cities justify climate policies, enhance accountability, and strengthen public support through evidence-based decision-making.
Crosswalking SBTN freshwater requirements with CSRD water disclosures
This report compares the SBTN freshwater framework with EU CSRD and ESRS requirements. It identifies areas of alignment, such as materiality assessments and basin-level analysis, while highlighting differences in scope. SBTN provides the scientific foundation for setting targets that support mandatory reporting obligations under European standards.
The business case for science-based targets: Corporate insights on the value of science-based targets for nature
This report examines the strategic value of science-based targets for nature. Drawing on insights from early adopters across diverse sectors, it identifies six key business benefits, including protected revenue and enhanced credibility. It outlines a structured approach for organisations to manage environmental impacts while future-proofing operations against regulatory shifts.
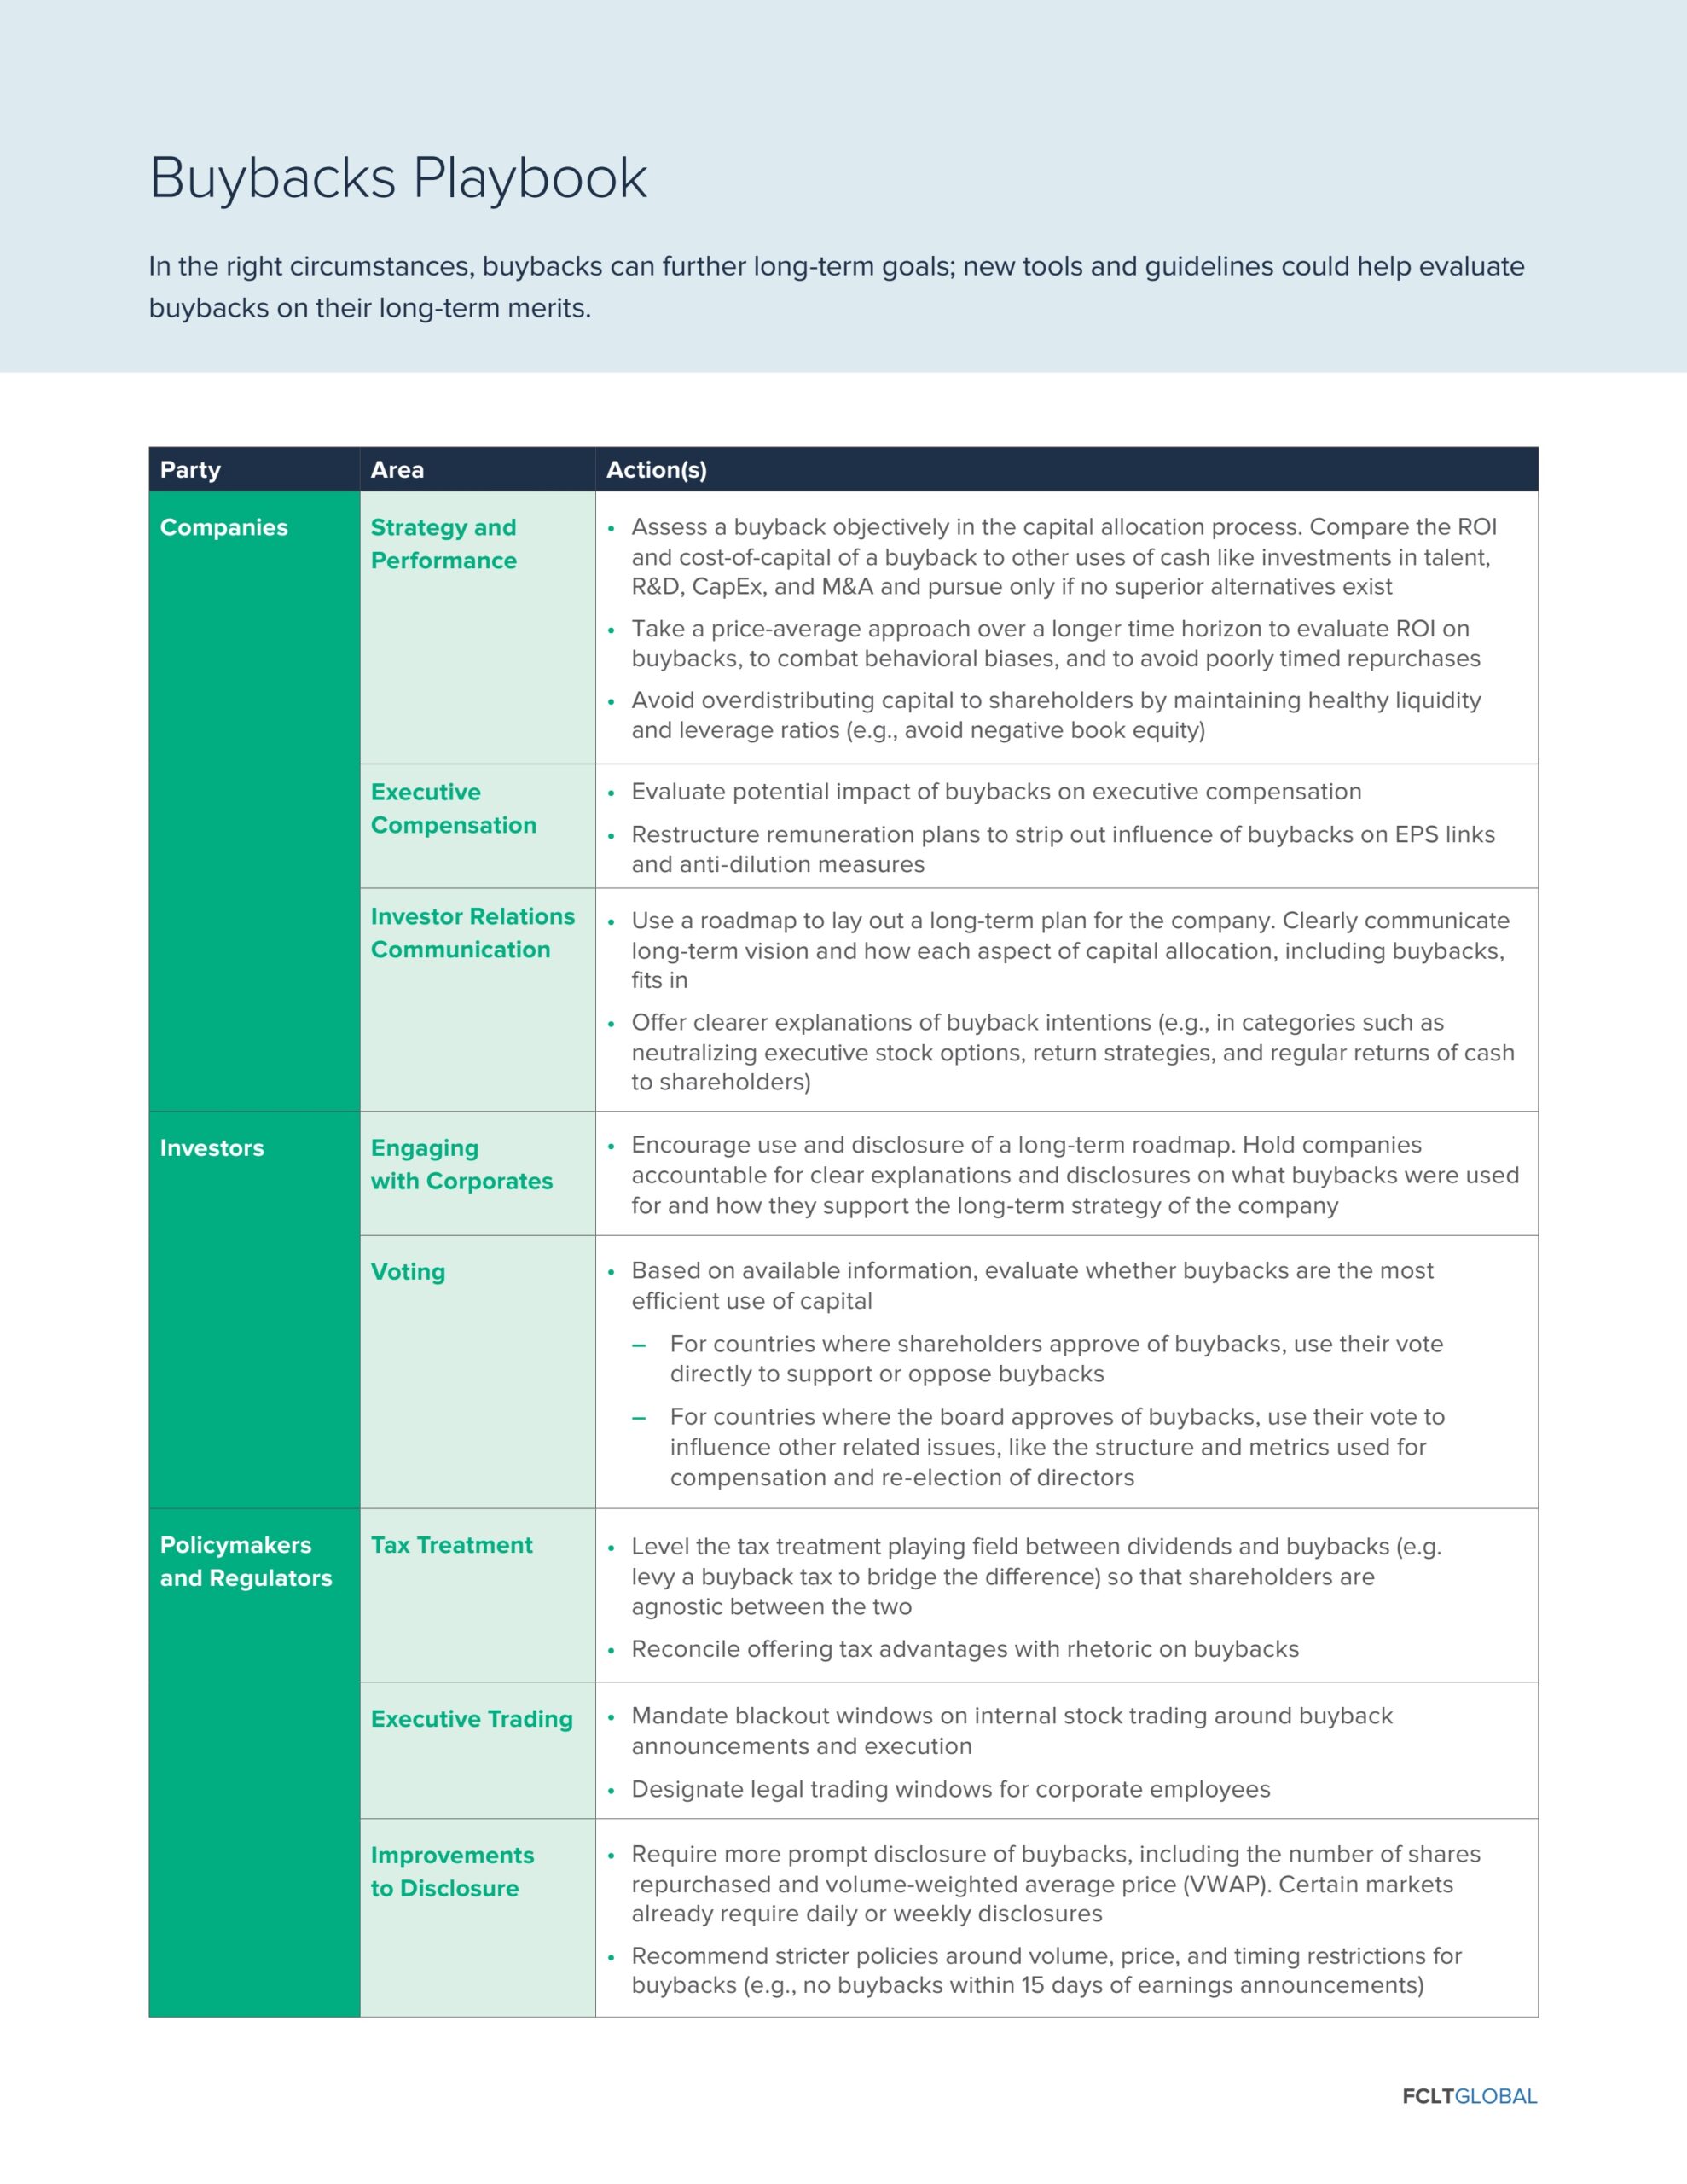
Buybacks playbook
This playbook provides a framework for companies, investors, and policymakers to evaluate share buybacks based on long-term merits. It recommends objective capital allocation, decoupling executive pay from buyback-influenced metrics, and enhancing regulatory disclosures and trading restrictions to ensure repurchases support sustainable corporate strategy rather than short-term gains.
Sustainability or strategy: Bridging the gap between climate change and long-term value creation
FCLTGlobal research identifies a significant gap between corporate climate commitments and long-term business strategies. Analysing the world’s 100 largest companies, the report introduces a Conversation Guide to help organisations integrate climate transition planning into core value creation, capital allocation, and risk management to build investor trust and resilience.
From voluntary to binding: Integration of sustainability standards and initiatives in public mining governance
This report examines the integration of sustainability standards and initiatives (SSIs) into public mining governance. Through surveys and case studies in Brazil, Madagascar, and Sweden, it demonstrates how voluntary standards complement mandatory regulations to address environmental, social, and governance risks, supporting policy formulation, implementation, and transparent reporting.
Administrative and market frictions in the choice between green and conventional bonds
This research investigates how administrative frictions and institutional environments influence corporate green bond issuance. Using global data from 2013–2024, it finds that bureaucratic complexity reduces green labelling probability, particularly outside transition-intensive sectors. Mandatory sustainability disclosure significantly increases issuance, highlighting the importance of efficient implementation for sustainable finance policies.
Sustainability assurance: Frequently asked questions: The application of materiality under ISSA 5000
This IAASB publication provides guidance on applying materiality under ISSA 5000. It explains concepts such as double materiality, performance materiality, and aggregation risk. The FAQs assist practitioners in planning and reporting on sustainability assurance engagements, clearly distinguishing between an entity's reporting process and a practitioner's assurance application.
Disability employment quotas: Lessons for Indonesia from ASEAN and East Asia
This report analyses disability employment quota systems across Indonesia, ASEAN, and East Asia. It identifies five legal models, ranging from binding levy-subsidy architectures to voluntary incentive-based approaches. Recommendations for Indonesia include clarifying calculation methodologies, establishing structured incentive frameworks, and implementing graduated compliance pathways to improve inclusive employment outcomes.
Enterprises, supply chains and the transition to formality: Linkages and innovation
This ILO research brief examines how multinational enterprises and supply chains drive the transition from informal to formal economies. By leveraging market incentives, technology transfers, and innovative procurement, MNEs can improve working conditions, social protection, and productivity for lower-tier MSMEs, supporting global decent work objectives.


